Competition in Kenya’s payments market is set to intensify following the entry of new local player into the card business, giving banks a local alternative to global payment networks Visa and Mastercard.
The move marks Kenswitch expansion of the fintech’s role from routing transactions between financial institutions to operating a domestic card scheme for issuing and accepting payment cards.
According chief executive John Mukono the move is positioning its scheme as a local infrastructure option for banks seeking to launch card products without relying entirely on international card networks.
“Our domestic card proposition is an important step in strengthening Kenya’s own payments capabilities and giving financial institutions an additional platform for domestic card issuance and transactions,” said Mukono.
The launch comes as Kenya’s card payments market continues to expand, with millions of consumers using debit, prepaid and credit cards for purchases and cash withdrawals.
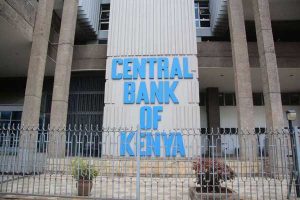
Central Bank of Kenya data shows that the number of payment cards stood at 13.76 million in July 2026. Debit cards accounted for 11.16 million, followed by 2.26 million prepaid cards and about 341,000 credit cards.
Payments made through point-of-sale terminals reached Sh297 billion in 2025.
CBK’s monthly figures show that POS transactions were worth Sh176.9 billion in the first seven months of 2026, excluding cash withdrawals.
Kenswitch said its network currently connects more than 2,200 ATMs, 50,000 point-of-sale terminals and 80,000 agent outlets.
Customers will obtain the cards through participating financial institutions, while Kenswitch is also developing support for contactless payments through smartphones and digital wallets.
The company is also exploring partnerships with technology firms and device manufacturers to allow customers to load virtual cards onto smartphones and other devices for contactless payments.
“We are looking beyond the card itself to how consumers will use payment credentials in the future,” Mukono said.
The shift towards digital credentials is being driven by the wider adoption of tokenisation, which replaces sensitive card information with a digital token when a transaction is processed.
Visa said tokenised credentials recorded a 39.4 percent lower fraud rate than non-tokenised credentials across its global network during its 2025 financial year. The figure is based on Visa’s global network and does not represent a projected fraud rate for Kenswitch.
Mastercard has also expanded the use of tokenised payments. In June 2025, the company said almost half of its European e-commerce transactions were tokenised as it works towards full tokenisation in that market by 2030.
The Kenswitch Card will use the company’s existing payments infrastructure to connect cards issued by participating financial institutions to ATMs, point-of-sale terminals and online payment channels.
The domestic card scheme will, however, compete in a market where mobile money already has a much wider consumer and merchant footprint.
CBK recorded 94.35 million registered mobile-money accounts and 575,400 active agents in July. The number of accounts includes multiple registrations by individual users.
International card networks have also been seeking closer links with Kenya’s mobile-money ecosystem.
Mastercard partnered with Safaricom in 2024 to expand payment acceptance and cross-border remittances, targeting more than 636,000 M-Pesa merchants.
Kenswitch’s entry therefore adds another layer to an increasingly competitive payments market, with banks, mobile-money operators, fintechs and global card networks competing for a larger share of digital transactions.