High government borrowing is keeping Kenya’s long-term capital tied up in state securities, making it harder for private infrastructure projects and businesses to attract funding, investment experts have warned.
Investment managers say pension trustees are increasingly being forced to weigh the relatively attractive returns offered by Treasury bills and bonds against the higher risks associated with infrastructure and other private-sector investments.
Government securities are offering yields of between 12 and 15 percent, making them difficult for riskier investments to compete with, according to fund managers speaking at a financial markets’ forum.
This is limiting the amount of capital flowing into productive investments despite the growing size of pension funds across Kenya.
Sanlam Allianz Investments chief executive Jonathan Stichbury said pension trustees are taking a rational approach when comparing investment opportunities.
“When you go to a board of trustees and say we would like to recommend an investment in a risky asset, they say, what is the non-risky asset yielding?” said Stichbury.
He said when the alternative is a government security yielding up to 15 per cent, trustees may opt to remain in government debt rather than take additional risk.
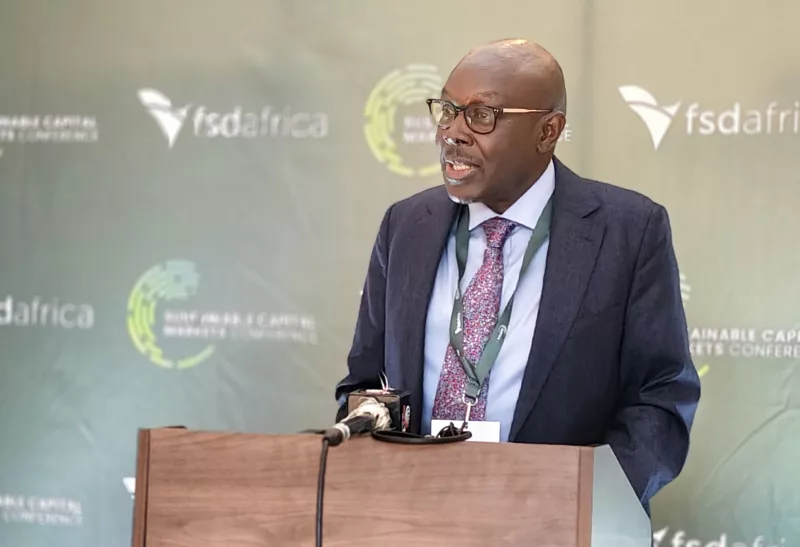
FSD Africa Chief Financial Markets Officer, Evans Osano noted that the situation creates a dilemma for Kenya as the Government seeks more private capital to finance infrastructure at a time when its own borrowing costs remain high.
Pension funds are among the largest pools of long-term domestic capital and are naturally suited to projects such as roads, energy, housing and other infrastructure because such investments can generate income over extended periods.
“The problem is not a lack of money but the limited number of investment products capable of attracting pension capital. Kenyan regulations allow pension schemes to invest up to 10 per cent of their assets in infrastructure, but actual allocations remain below one percent,” said Onsano.
This leaves a significant gap between what pension funds are legally allowed to invest and what they are actually putting into infrastructure projects.
The gap comes as the Government increasingly looks to private investors to take on a larger role in financing development projects because of constrained public finances.
However, National Treasury in its The Annual Borrowing Plan holds that the government securities will remain the main instrument for mobilising domestic financing.
“The primary instrument for mobilizing domestic financing will be the issuance of Government securities, with a strategic emphasis on Treasury bonds,” the National Treasury said.
The government plans to issue Treasury bonds with maturities ranging from two to 25 years, alongside infrastructure bonds.
Onsano said reducing the infrastructure financing burden on the Government could eventually help lower the amount it needs to borrow.
That could, in turn, ease pressure on interest rates and make private-sector investments more competitive.
“If we can take that infrastructure burden away from government… government should then have to raise less money. And interest rates can come down,” he said.
This can raise the cost of capital for businesses and infrastructure developers, potentially delaying projects or making some investments financially unviable.
Fund managers also want more structured investment products that pension trustees can understand and assess more easily.
“Bespoke infrastructure projects can be difficult for trustees to approve because of the risks involved and the complexity of their structures. However, securitisation is emerging as one potential solution,” said FSD Africa CEO Mark Napier.
Kenya developed a policy and regulatory framework for securitisation about 18 years ago, but no transactions took place for much of that period. That has started to change, with three securitisation transactions completed in less than a year
Securitisation allows specific assets or future cash flows to be packaged into investable instruments, potentially making projects easier for institutional investors to assess.
The transactions have included structures supporting small-scale farmers, including financing for agricultural inputs and solar-powered irrigation equipment.
The financial experts said such structures could make alternative investments easier for pension trustees to understand because they provide clearly defined assets and cash flows.
They lauded the infrastructure fund’s potential to provide another channel through which institutional capital can participate in infrastructure development.
But fund managers say having money available is not enough, they argue that there must be a pipeline of bankable projects with predictable cash flows, adequate risk protection and clear exit mechanisms.
The financial experts noted that political and currency risks remain among the concerns that need to be addressed before pension funds can commit significant amounts to infrastructure.