The Institute of Certified Public Accountants of Kenya (ICPAK) says only a small number of companies have made significant progress in preparing to provide information on issues such as climate change, environmental impact and how these issues could affect their businesses.
The ICPAK Sustainability Reporting Readiness Assessment 2026 found that the 385 entities that submitted substantive responses scored an average of 1.51 out of four on preparedness.
These new standards will become mandatory for public interest entities for accounting periods beginning on or after January 1, 2027, leaving roughly four months to the effective date.
Of the 385 entities assessed, 289, or 75 percent, were in the Nascent or Emerging categories, while only 23 entities, representing six per cent, had reached the Advanced stage.
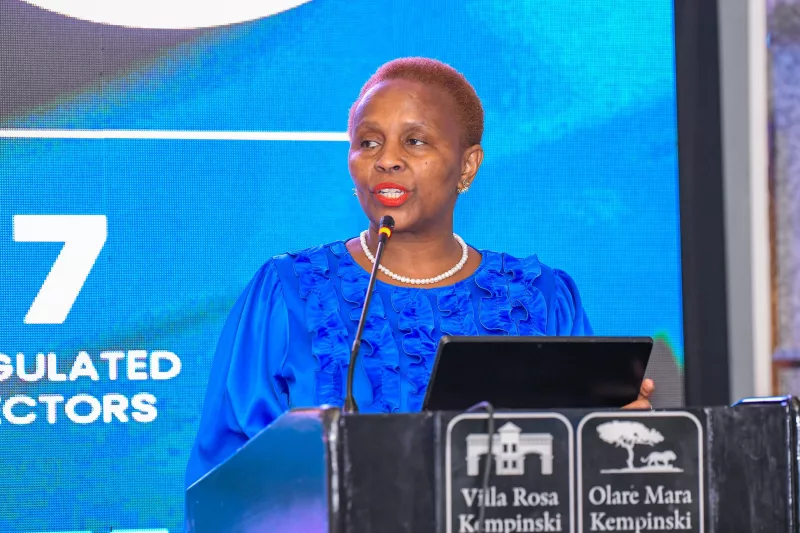
“Of the 512 entities in the assessment register, 444 completed the assessment, representing an 86.7 per cent completion rate. Of these, 385 provided substantive responses that were included in the scoring analysis. The national readiness score is 1.51 out of 4, placing the market in the report’s ‘Emerging’ band,” said ICPAK chair Elizabeth Kalunda.
The findings point to a wide gap between companies’ stated commitment to sustainability and their ability to produce the detailed, reliable and auditable information required under the new framework.
ICPAK said the biggest weakness is the ability of companies to collect and report measurable information on sustainability issues.
Governance was the strongest area, scoring 1.60 out of four, while metrics and targets scored just 1.22.
The findings further note that companies are increasingly putting people in charge of sustainability issues, but many are struggling to produce the actual figures and information needed to back up their claims.
The gaps include areas such as measuring carbon emissions, setting targets to reduce emissions and linking management incentives to sustainability targets.
The report found significant differences across sectors. Other listed companies recorded a readiness score of 2.40, followed by State corporations reporting under IFRS at 2.23 and commercial banks at 2.04.
Fund managers scored 1.73, insurance companies 1.63, pension schemes 1.34 and deposit-taking SACCOs 1.26.
ICPAK chief executive Grace Kamau said the findings should be used by companies to identify areas where they need to improve rather than simply as a measure of compliance.
“As we launch this assessment, let us treat it not as a final judgement, but as a baseline for action. It should help entities understand their gaps, prioritise investments and strengthen their reporting systems,” Kamau said.
She said the findings should also help regulators identify areas where companies need support, while accountants and auditors prepare for the new reporting requirements.
Capital Markets Authority director of corporate services Mathew Mukisu, said listed and large companies were increasingly moving towards mandatory and assured sustainability disclosures.
“Kenya cannot stand apart from this shift. Our listed companies compete for capital. Investors are increasingly seeking comparable information on how companies manage climate risk, resource use, human capital and governance before providing funding,” said Mukisu.
He warned that companies unable to provide credible information could face higher financing costs or see capital move elsewhere, while better-prepared entities could attract greater investor interest.
The assessment also found weaknesses in the quality and assurance-readiness of existing sustainability disclosures.
Decision-usefulness and faithful representation scored 1.77 out of four, while data and systems readiness scored 1.76. Connectivity of information scored 1.49, completeness and use of guidance 1.45, and assurance readiness 1.54.
This means that even entities already publishing sustainability information still face challenges linking those disclosures to financial reporting, supporting them with reliable data and ensuring they can withstand independent scrutiny.
The assessment also found that only 25 percent of substantively assessed entities had reached either the Developing or Advanced readiness bands, despite 69.5 percent of respondents in an earlier 2024 survey expecting to be ready by 2026.