Insurance regulators across East Africa are moving to standardise the way insurance companies are supervised, in a push to make it easier to compare underwriting practices and strengthen oversight of the region’s growing insurance market.
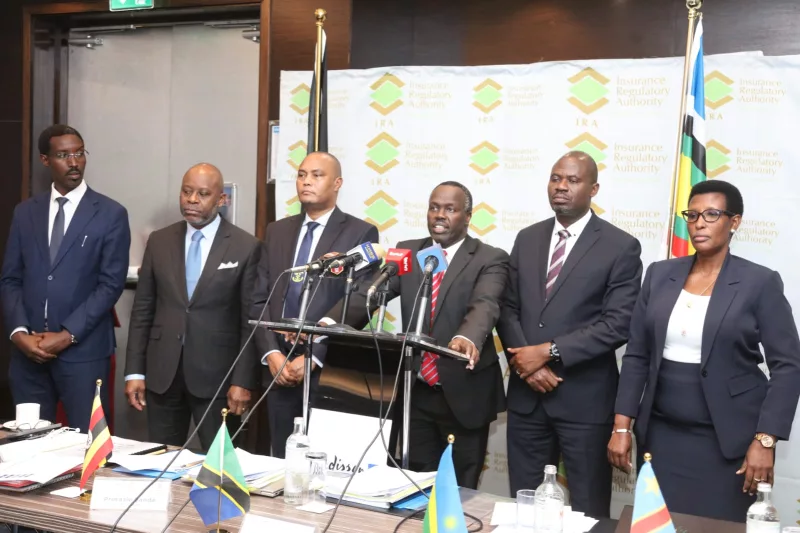
The move was agreed by commissioners and insurance supervisors from several East African countries during a two-day meeting held under the East African Association of Insurance Supervisors (EASA).
The regulators agreed to harmonise the template used to assess compliance with insurance core principles, creating a common basis for evaluating insurers across the region.
Insurance provision is guided by 25 insurance core principles, but regulators have been assessing compliance differently in their respective countries.
The associations chair Protazio Sande, said the harmonised approach would allow regulators to assess individual markets while also comparing their performance with regional peers.
“We have agreed to harmonise a template so that we can do assessment at country level, but also compare with our peers. The standardisation is expected to strengthen supervisory consistency as insurers increasingly operate across borders and take on more complex risks,” said Sande.
The regulators also agreed to develop a regional integrated insurance supervisory software that would allow them to access and exchange information in real time.
They argue that increasing digitisation of insurance had made traditional methods of collecting information from individual market players less effective.
“For us to be in charge and do effective supervision, we need to be enabled by a software. The proposed system will allow supervisors to use the same platform while sharing information and comparing developments across markets,” he said.
The regulators are also seeking to harmonise digital transformation practices in the insurance sector. Countries in the region are at different stages of digitisation, with some having advanced practices in areas such as distribution and mobile-based insurance services.
The regulators want to document these practices and share them across the region to help markets adopt approaches that can improve access to insurance.
The push for common oversight comes as East African insurers face growing demand to cover larger and more complex risks, including those arising from mining, oil and gas and other emerging economic activities.
Regulators said insurance companies are increasingly required to hold capital in line with the risks they underwrite, rather than relying solely on minimum capital requirements.
Under the risk-based capital approach, insurers face additional capital charges depending on the risks they take on. Companies seeking to underwrite larger risks may therefore have to raise additional funds from shareholders.
The regulators also pointed to mergers and acquisitions in the region as evidence of insurers seeking to become stronger and increase their capacity to absorb emerging risks.
Despite concerns over the ability of local insurers to handle large risks, regulators said the region has capacity to underwrite significant risks, with international reinsurance markets available where local capacity is insufficient.
The regional supervisors also agreed to establish a common complaints-management framework to improve policyholder protection.
The framework is intended to ensure that consumers receive broadly similar standards when resolving insurance complaints regardless of whether they purchased cover in Kenya, Tanzania, Rwanda, Uganda or Burundi.
The regulators are further working on a unified constitution for EASA and a governance charter to provide a common institutional framework for the association.
Sande said the various resolutions were expected to make significant progress within one year, although the adoption of the common constitution could take longer because countries have different legal procedures.
The regulators said stronger coordination would ultimately support the development of East Africa’s insurance markets by improving supervisory effectiveness, sharing information and creating more consistent standards for insurers operating in the region.